A 401(k) is a workplace retirement plan that can help you prepare for life beyond your working years. It deserves a place in your financial plan alongside housing, current bills, and emergency savings. Start by understanding what your employer’s plan offers and how its contributions fit your budget.
Know what happens on payday
Eligible employees can generally direct part of their pay into a 401(k). Traditional pretax contributions generally reduce current federal taxable income, while designated Roth contributions, if the plan offers them, are made after tax. Qualified Roth distributions can be tax-free. Eligibility, contribution limits, and withdrawal rules matter; review the plan and current IRS guidance before choosing an approach.
Understand the employer contribution
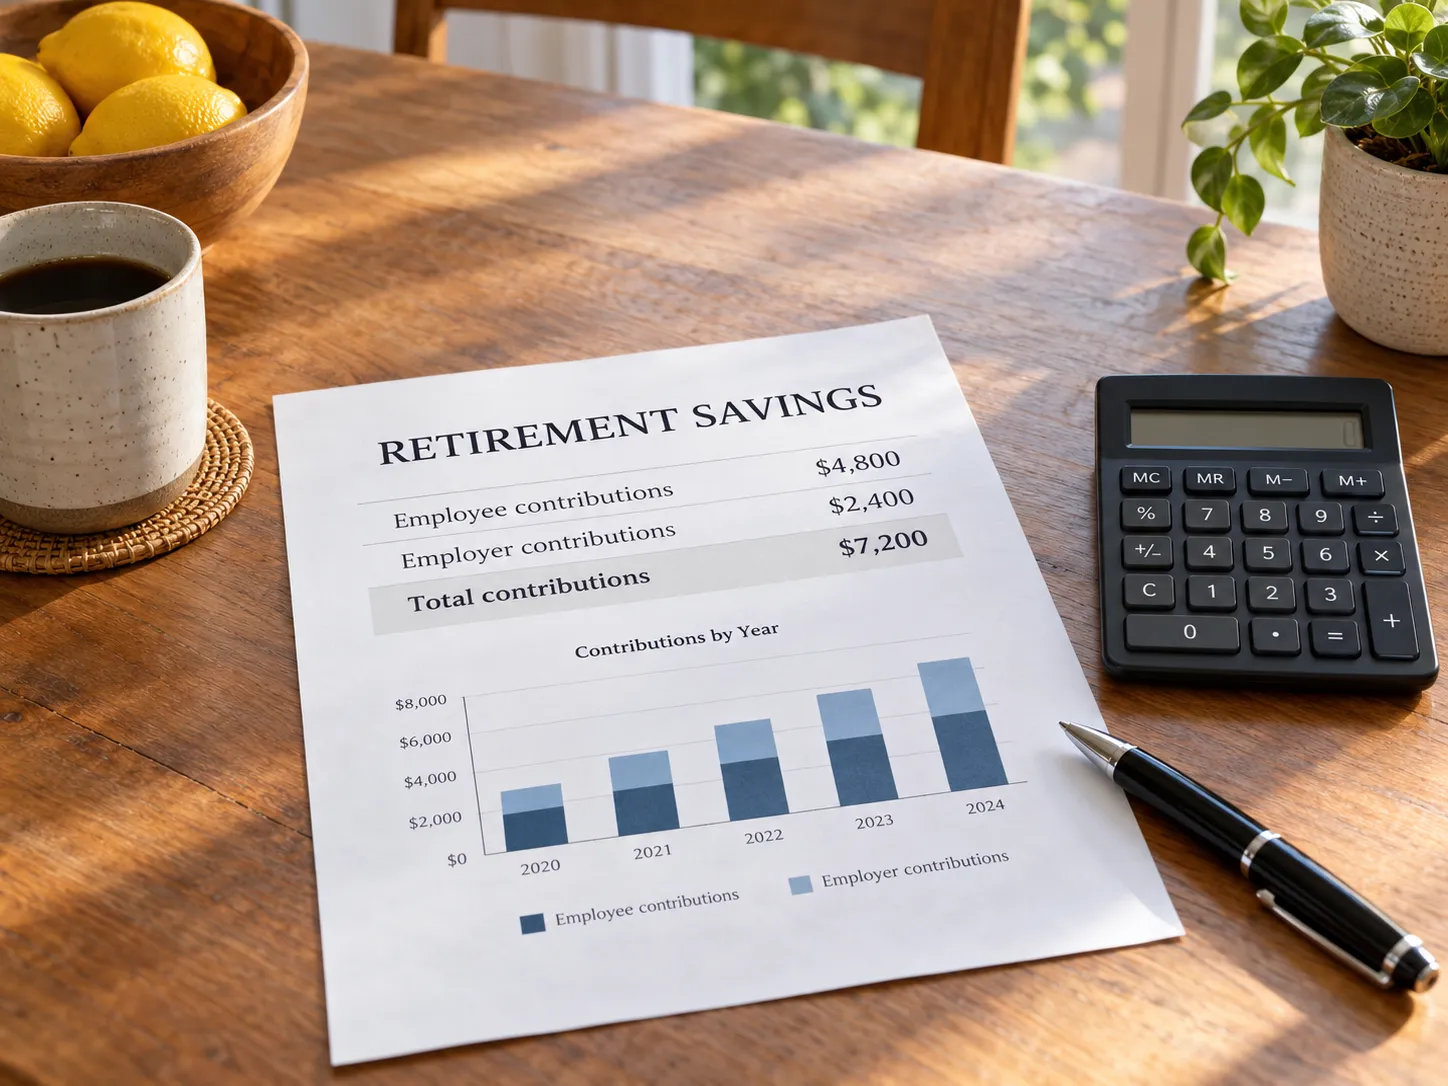
If your employer offers a match, ask how it is calculated and what you must contribute to receive it. Also ask about vesting: some employer contributions become yours over time under the plan’s rules. A contribution example on a statement does not mean every employer offers the same arrangement.
Read more than the account balance
Review contribution elections, the investments selected, fees, beneficiaries, and the plan’s Summary Plan Description. An account can gain or lose value, and fees affect what remains. If the terminology feels unfamiliar, ask the plan administrator to explain it before making a change.
Keep retirement and home goals in the same conversation
A down payment can feel urgent because it has an immediate destination. Retirement may feel farther away, but both goals compete for the same monthly income. Put a proposed housing payment beside retirement contributions, everyday expenses, and an emergency reserve. That comparison helps you see whether a home fits your broader priorities.
Do not treat a withdrawal as ordinary savings
A retirement account is subject to access and tax rules. A distribution before age 59½ can bring an additional 10% tax unless an exception applies, and other taxes may also apply. A plan loan, if available, has its own terms. Before using retirement money for a purchase or emergency, discuss the consequences with the plan administrator and a qualified tax or financial professional.
Turn a statement into a useful conversation
You do not have to settle every retirement decision in one afternoon. Confirm your current contribution, understand the match and fees, and choose a time to review the plan again. When a housing decision comes up, bring that information into your budget so the move supports both your present life and the future you are building.