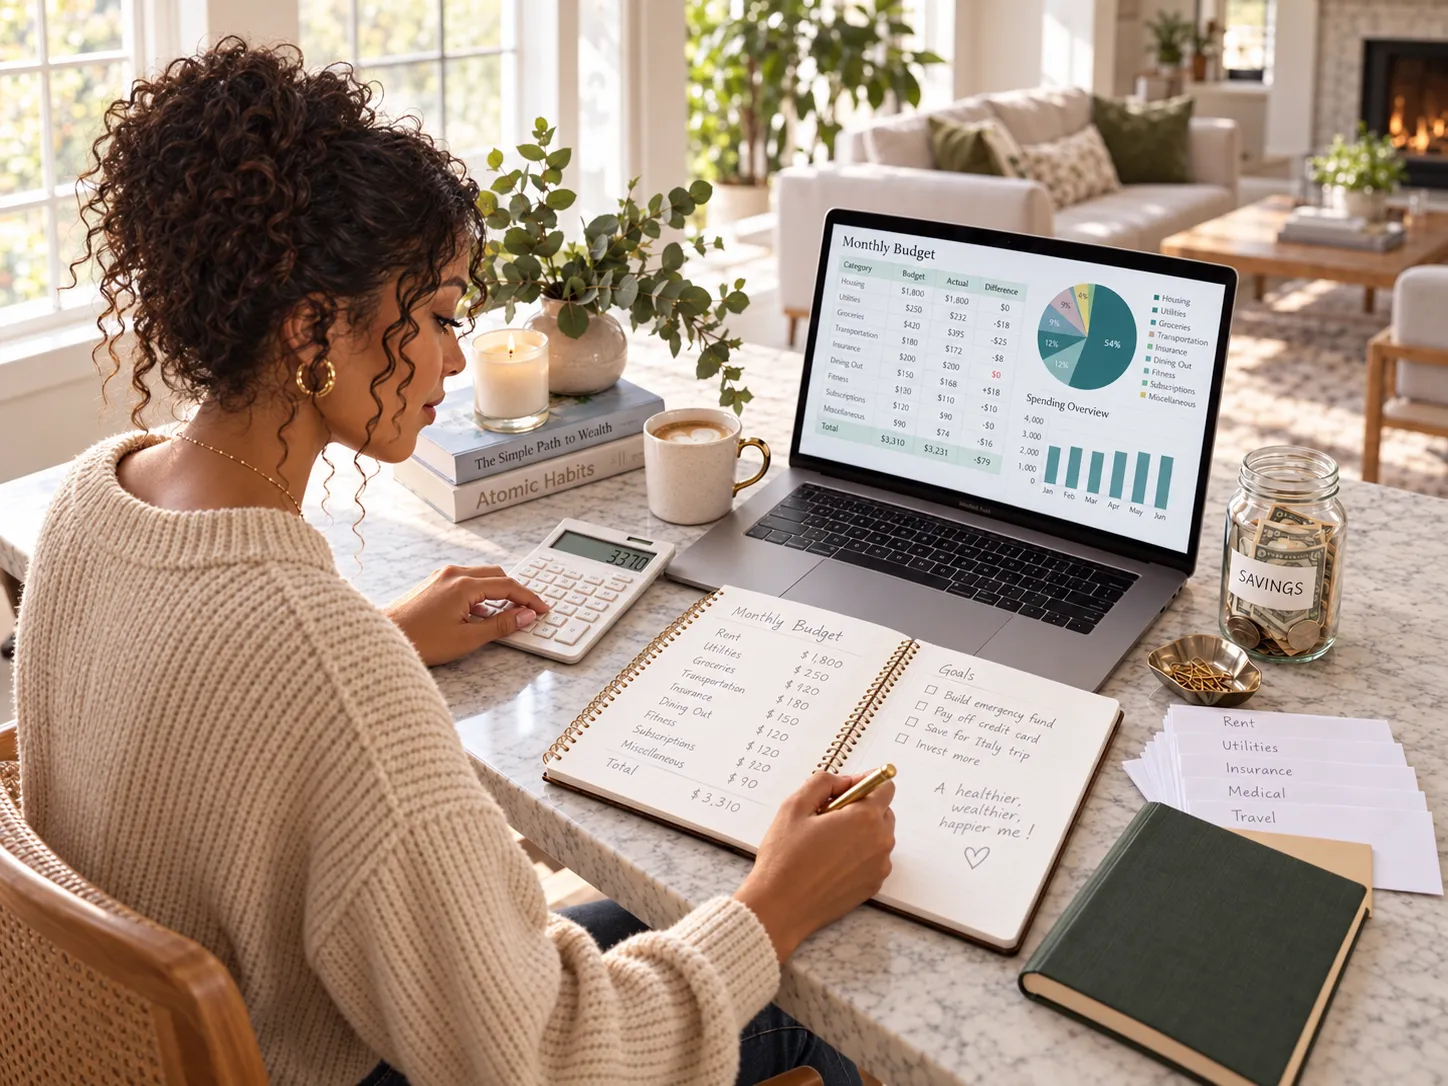
A budget is not a restriction on your future. It is a way of choosing it. When you decide where your income goes before the month begins, you make room for the things that matter—your bills, your goals, your peace of mind, and even the things you enjoy.
You do not need a perfect spreadsheet or a high income to begin. You need honest numbers, a few priorities, and the willingness to adjust as you learn.
A budget is a plan for living, not a punishment
A useful budget answers three questions: what money is coming in, where it needs to go, and what you want it to make possible. When your spending is visible, you can make intentional tradeoffs instead of wondering at the end of the month where everything disappeared.
Budgeting can support a home purchase, a move, retirement, less financial stress, or simply the ability to buy groceries without anxiety. It is not about depriving yourself of every pleasure. A budget that never leaves room for enjoyment is unlikely to be a plan you want to keep.
Start with your real take-home pay—the money available after taxes and payroll deductions—not the salary figure on an offer letter. If your income changes from month to month, use a conservative baseline and give extra income a job only after it arrives.
Give every dollar a purpose
One simple method is called zero-based budgeting. You assign every dollar of expected income to a category: bills, groceries, transportation, debt, savings, gifts, fun, irregular expenses, and so on. At the end of the planning process, income minus all assignments equals zero. Zero does not mean you spent everything; money set aside in savings also has a job.
For example, with $4,500 in monthly take-home pay, your plan might assign $1,600 to housing, $380 to utilities, $500 to groceries, $400 to transportation, $600 to debt payments, $300 to savings, $400 to personal spending, and $320 to irregular expenses. Together, those assignments total $4,500.
The exact categories will depend on your life. The value comes from making the decisions deliberately, not copying someone else’s percentages. Use these categories as a starting point, then adjust them to fit your own expenses and goals.
Start with what you actually spend
Look back over two or three months of bank and card statements. Capture fixed bills like rent, mortgage, phone, and insurance, but also flexible costs like food delivery, coffee, subscriptions, gas, and small online purchases.
Do not forget the expenses that happen only a few times a year: car registration, holidays, school supplies, travel, gifts, repairs, and annual subscriptions. Divide an expected yearly cost by 12 and save that amount each month in a dedicated sinking fund. A $600 annual bill becomes a manageable $50 monthly assignment rather than a surprise.
This part is about observation, not embarrassment. You are learning what your life costs so you can choose what you want to change.
Build savings into the plan from the beginning
If you wait to save whatever is left at the end of the month, you may find that very little remains. Try treating savings as a planned category, even if you begin with $10 or $25. Automating a transfer shortly after payday can help make it consistent.
Think of saving in layers: a small buffer in checking, a starter emergency fund for unexpected expenses, and longer-term goals such as a home down payment or retirement. Keep near-term emergency money in an accessible, appropriate account rather than exposing it to investment risk you cannot afford.
If you are paying down high-interest debt, compare the benefits of reducing interest with the need to maintain a cash cushion. You do not have to solve every financial goal at once; you need a sensible order of operations.
How to find money to save without making life miserable
Begin with the biggest repeatable opportunities. Review housing and transportation costs when your circumstances allow, compare insurance renewals, cancel services you genuinely do not use, and plan meals around ingredients you already have. A few sustainable changes usually beat an extreme one-week spending freeze.
Try setting a weekly flexible-spending amount for takeout, entertainment, and miscellaneous shopping. When one category runs high, move money from another category consciously instead of ignoring the difference. This turns a budget into a tool you can adjust rather than a test you pass or fail.
If you spend $80 less each month, that is $960 over a year before interest. The amount may sound small, but intentional consistency is what creates options over time.
Make the budget work with your home goals
If you hope to buy a home, plan for more than a down payment. Closing costs, inspections, moving, initial repairs, property taxes, insurance, utilities, HOA dues when applicable, and an emergency reserve all belong in the full picture.
When evaluating a home, compare the total expected monthly ownership cost with the payment that allows you to keep living your life. A lender can explain financing terms, and Dominique can help you connect the home search with what matters to your household.
For current homeowners, a budget can help prepare for maintenance, assess whether a renovation fits, and make decisions about selling, renting, or investing with more clarity.
Review, adjust, and keep going
Spend 15 minutes once a week checking what cleared, what is still pending, and which categories need attention. At month-end, compare the plan with reality. You are allowed to revise the numbers when your life changes.
Try not to think of an over-budget month as a personal failure. Ask what caused the gap: Was an expense unpredictable, or did the original plan overlook something important? Use the answer to improve next month.
The point of budgeting is not to become perfect with money. It is to create more control, more peace, and more room for the life you are building.
Fifteen minutes can change how your month feels.
Check your balances, review upcoming bills, move money between categories if needed, and celebrate progress. A budget works best when it is a flexible conversation with reality—not a harsh set of rules.
Your target housing payment should leave room for groceries, travel, repairs, retirement, emergencies, and the people you love. The maximum a lender approves is not necessarily the amount you will feel comfortable paying.